A
Anonymous
Financial expert · Financer
 Reviewed by Ricardo Laizo
A debt-to-income ratio (DTI) is your total monthly debt payments divided by your gross monthly income, expressed as a percentage. It tells lenders how much of your paycheck is already committed to existing debts.
For example, if you pay $2,000 per month toward debts and earn $6,000 per month before taxes, your DTI ratio is 33%. Lenders use this number to gauge whether you can realistically handle additional monthly payments on a new loan or credit card.
DTI is one of the first things mortgage lenders, auto lenders, and credit card issuers check during an application. A high DTI signals financial strain. A low one suggests you have breathing room in your budget.
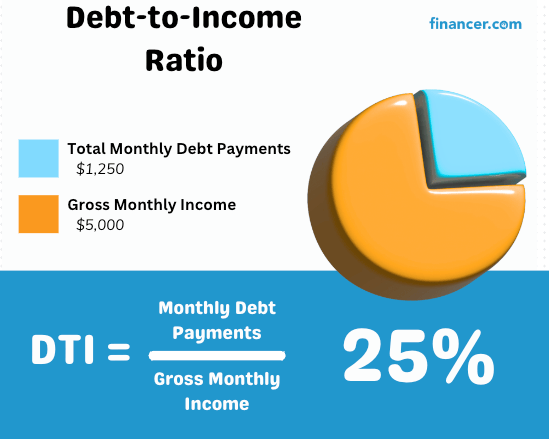
The debt-to-income ratio formula is straightforward:
DTI = (Total Monthly Debt Payments / Gross Monthly Income) x 100
Here is a quick example. Say you have the following monthly debt payments:
Your total monthly debt is $2,100. If your gross monthly income (before taxes) is $6,000, your DTI is:
$2,100 / $6,000 = 0.35, or 35%
That puts you right at the edge of what most lenders consider a healthy ratio.
List All Monthly Debt Payments
Write down every recurring monthly debt payment: credit card minimums, car loan, student loan, mortgage or rent, personal loan payments, child support, and alimony. Only include the monthly payment amount, not the total balance owed.
Tip: Pull up your bank statements or loan accounts to make sure nothing slips through.
Add Up Your Total Monthly Debts
Sum all the monthly payments from step one. For example, if your mortgage is $1,400, car loan is $350, and credit card minimum is $150, your total is $1,900 per month.
Determine Your Gross Monthly Income
Your gross income is what you earn before taxes and deductions. Include your salary, regular bonuses, freelance income, rental income, and any other consistent income sources.
If your income fluctuates (freelancers, gig workers), average your earnings over the past 12 months for a more accurate figure.
Divide and Multiply
Divide your total monthly debts by your gross monthly income. Multiply the result by 100 to get a percentage.
Example: $1,900 / $5,500 = 0.345, or 34.5% DTI.
Different DTI ranges send different signals to lenders. Here is how most financial institutions evaluate your ratio:
| DTI Range | Rating | What It Means |
|---|---|---|
35% or less | Excellent | You have plenty of income left after debt payments. Lenders view you favorably, and you are likely to qualify for the best rates. |
36% to 43% | Manageable | You are carrying a moderate debt load. Most lenders will still approve you, but interest rates may be slightly higher. |
44% to 50% | Concerning | You are approaching risky territory. Some lenders may decline your application or require compensating factors like a large down payment. |
Above 50% | High Risk | More than half your income goes to debt. Loan approval becomes difficult, and it may be time to focus on reducing debt before borrowing more. |
Each loan program sets its own DTI ceiling. If your ratio is on the higher side, some programs are more flexible than others:
| Loan Type | Typical Max DTI | Notes |
|---|---|---|
Conventional (Fannie/Freddie) | 45-50% | Up to 50% with strong compensating factors (high credit score, large reserves) |
FHA Loans | Up to 57% | Most flexible for borrowers with higher debt loads |
VA Loans | Up to 60% | No hard cap, but lenders review residual income closely |
USDA Loans | 41-46% | Front-end ratio capped at 29% |
Personal Loans | Varies (36-50%) | Online lenders tend to be more flexible than banks |
Credit Cards | No formal cap | Issuers evaluate DTI but don't publish specific thresholds |
Find the best personal loan in minutes through our comparison. 100% free and easy to use.
Start comparing personal loans now!Mortgage lenders look at two types of DTI:
Front-end DTI (housing ratio) includes only housing-related costs: your mortgage payment, property taxes, homeowner's insurance, and HOA fees. Lenders generally want this below 28%.
Back-end DTI (total ratio) includes all monthly debt obligations on top of housing costs: credit cards, car loans, student loans, personal loans, child support, and alimony. This is the number most people refer to when they say "DTI ratio," and lenders typically prefer it below 36%.
When you see a lender reference the "28/36 rule," they mean a front-end ratio of 28% or less and a back-end ratio of 36% or less. This is considered the sweet spot for mortgage qualification.
Lenders count all recurring monthly debt obligations when calculating your DTI. Here is what typically gets included:
Lenders consider all verifiable, recurring income when calculating your DTI:
If your DTI is too high for the loan you want, you have two levers to pull: reduce your monthly debt payments or increase your income. Here are the most effective strategies:
Your debt-to-income ratio does not directly affect your FICO credit score. Credit bureaus don't have access to your income information, so DTI is not part of the scoring model.
That said, DTI and your credit score are related in practice. High debt levels often go hand-in-hand with high credit utilization (the percentage of your available credit you are using), which does affect your score. The credit utilization ratio is the second-biggest factor in your FICO score after payment history.
Think of it this way: your credit score tells lenders how reliably you pay your debts. Your DTI tells them whether you can afford to take on more.
Here is how DTI works out at various salary levels, so you can see where you might land:
| Annual Income | Gross Monthly Income | Max Debt at 36% DTI | Max Debt at 43% DTI |
|---|---|---|---|
$40,000 | $3,333 | $1,200 | $1,433 |
$60,000 | $5,000 | $1,800 | $2,150 |
$80,000 | $6,667 | $2,400 | $2,867 |
$100,000 | $8,333 | $3,000 | $3,583 |
$120,000 | $10,000 | $3,600 | $4,300 |
A DTI above 43% does not automatically disqualify you from borrowing, but it does narrow your options.
With a high DTI, you may face higher interest rates on any loan you qualify for. Some lenders will decline your application outright. Others may approve you but with stricter conditions, like a larger down payment or a co-signer.
For mortgages specifically, government-backed programs like FHA loans tend to be more flexible, accepting DTIs up to 57% with compensating factors. VA loans can go even higher if your residual income is strong.
If you are struggling with high debt, consider exploring debt consolidation or creating a payoff plan with our guide on how to get out of debt.
A DTI of 36% or below is considered good by most lenders. Some mortgage programs accept ratios up to 43-50%, but you will generally get better rates and terms with a lower ratio.
Add up all your monthly debt payments (mortgage, car loan, student loans, credit card minimums, etc.) and divide by your gross monthly income. Multiply by 100 to get a percentage. For example, $2,000 in monthly debts divided by $6,000 gross income equals a 33% DTI.
Yes. If you are renting, your monthly rent payment is included in your DTI calculation. If you are applying for a mortgage, lenders will replace your rent with the projected mortgage payment (including taxes and insurance) to calculate your future DTI.
It depends on the loan type. Conventional loans typically cap at 45-50%, FHA loans allow up to 57%, and VA loans can go up to 60%. The standard Qualified Mortgage threshold is 43%, but many programs have exceptions for strong borrowers.
You can lower your DTI by paying off existing debts (start with small balances), avoiding new debt before applying for a loan, increasing your income, refinancing existing loans for lower monthly payments, or consolidating debt.
No, your DTI does not directly impact your credit score because credit bureaus do not have access to your income data. However, high debt levels often correlate with high credit utilization, which does affect your score.
Use gross income (before taxes and deductions). This is the standard that lenders use. Calculating with net income would give you a higher DTI than what lenders actually see.
The most common mistakes include forgetting to count co-signed loan payments, using net income instead of gross income, leaving out small debts like medical payment plans, and not including projected payments on a new loan you are applying for.
Do you have a question about this topic? Ask the community.
Email confirmed — your comment appears after review.
That link expired. Post your comment again.
Anonymous
Financial expert · Financer
Compare top lenders
from 1% APR
48 options
Join *Financer Stacks* - Your weekly guide to mastering money basics, stacking extra income, and creating a life where money works for you.