we can't guarantee the complete accuracy on a day-to-day
Filters
Interest free period
Annual fees
Benefits
Network
Product Statistics
A complete breakdown of all data points across the products in this comparison to help you make the right decision.
Cash back
5 (71.4%)
Rewards
5 (71.4%)
Secured
3 (42.9%)
Personal
7 (100%)
Balance transfer
1 (14.3%)
Annual fee
$0 - $35 ($5.83)
APR range
14.99% - 29.99% (24.62%)
Interest free period
21 - 25 (23.57)
Base reward rate
1% - 2% (1.5%)
Extended warranty
1 (14.3%)
Minimum age
18 - 18 (18)
Statistics based on 7 Credit cards products in our database.
CompanyLowestHighest
Upgrade14.99%29.99%
Citi17.49%27.49%
Capital One18.49%28.49%
OpenSky23.89%23.89%
Chase18.24%27.74%
Capital One29.74%29.74%
Discover27.24%27.24%
APR range
See how rates compare across all providers. The bars show the range between lowest and highest rates offered by each company.
Historical Best cashback credit cards Interest Rates
Average rates tracked monthly across 1 providers
Average rates tracked monthly across 1 providers
Average
Lowest
Highest
Aug 2025
21.31%
15.25%
26.31%
Sep 2025
21.65%
15.32%
26.65%
Oct 2025
21.88%
15.37%
26.88%
Nov 2025
21.94%
15.38%
26.94%
Dec 2025
21.77%
15.35%
26.77%
Jan 2026
21.4%
15.27%
26.4%
Feb 2026
20.87%
15.17%
25.87%
Mar 2026
20.28%
15.05%
25.28%
Apr 2026
19.73%
14.94%
24.73%
May 2026
19.32%
14.86%
24.32%
Jun 2026
19.11%
14.81%
24.11%
Jul 2026
19.13%
14.82%
24.13%
Aug 2026
19.99%
14.99%
24.99%
Current Average19.99%↑ 0.86pp
Lowest Available14.99%
Highest Available24.99%
Providers Tracked1
Financer's Choice
Top Rated
Upgrade
APRs range from 7.74% to 35.99%. Origination fees of 1.85% to 9.99% are deducted upfront, which is higher than average. No prepayment penalties. Checking account holders receive up to 20% rate discounts.
Support available by phone and email with generally prompt responses. No live chat option. Customer service reps are knowledgeable about loan terms and the application process.
Repayment terms of 24-84 months with transparent fee disclosures. Joint applications and secured loan options add flexibility. Lowest rates require Autopay and direct creditor payments.
A+ BBB rating. Users praise the fast application and quick funding. Some complaints about credit line decreases and account closures. Overall, the majority report positive experiences.
Get exclusive conditions from the best financial companies
Best Cashback Credit Cards in the US 2026
The best cashback credit cards are the ones that match how you already spend, not the ones with the loudest bonus. For most people, that means a simple 2% flat-rate card for everything, plus one category card for groceries, gas, dining, PayPal, Venmo, or rotating 5% categories.
Our short list starts with PayPal Cashback Mastercard, Venmo Credit Card, Wells Fargo Active Cash, Citi Double Cash, Chase Freedom Flex, Blue Cash Everyday from American Express, and U.S. Bank Cash+. Each one can make sense, but not for the same household. The right choice depends on whether you want zero maintenance, higher category rewards, or a card that plugs into an app you already use.
If you are still choosing your first card type, start with our credit cards guide. If your goal is broader points or travel value, compare this page with our rewards credit cards guide before you apply.
Top Cashback Picks and What They Are Best For
Here is the practical way to think about cashback credit cards compared side by side. Flat-rate cards are easiest. Bonus-category cards pay more when your spending is concentrated. Rotating category cards can be excellent, but only if you remember to activate categories and use the card at the right merchants.
We included PayPal and Venmo because they solve two very specific use cases. PayPal is useful if a lot of your online checkout already runs through PayPal. Venmo is useful if your spending naturally shifts between groceries, dining, bills, travel, and gas, because it automatically finds your top eligible categories.
3% top eligible category, 2% next, 1% other eligible purchases
$0
Chase Freedom Flex
Quarterly category optimizers
5% rotating categories up to quarterly cap, plus dining and drugstore bonuses
$0
Blue Cash Everyday from American Express
Groceries, gas, and online retail
3% in three everyday categories up to annual caps, then 1%
$0
U.S. Bank Cash+
People who can choose categories each quarter
5% on two selected categories up to quarterly cap, 2% one everyday category
$0
Flat Rate vs Tiered vs Rotating Cashback Cards
There are three main reward structures. Once you understand them, the whole comparison becomes much easier.
Flat rate cashback cards pay the same rate, or nearly the same rate, on most purchases. These are the easiest cards to use well because there are no categories to memorize. A 2% flat-rate card is often the best default card for bills, repairs, medical copays, subscriptions, and random purchases that do not fit a bonus category.
Tiered or bonus-category cards pay a higher rate in defined categories. Venmo, Blue Cash Everyday, and many grocery or dining cards fit here. They can beat flat-rate cards if your household spending is predictable. If you spend a lot at U.S. supermarkets, gas stations, restaurants, or online retailers, the math can work quickly.
Rotating category cashback cards can pay some of the highest rates, but they ask more from you. Chase Freedom Flex, for example, requires quarterly activation for its 5% bonus categories. U.S. Bank Cash+ lets you choose categories, but you need to make those choices on schedule. These cards reward attention. They punish forgetfulness.
Structure
Typical earn rate
Best user
Main drawback
Flat rate
1.5% to 2% on most purchases
Someone who wants one card
Lower upside on groceries, gas, dining, and travel
Tiered category
3% to 6% in selected categories
Someone with predictable spending
Caps, exclusions, and merchant coding can reduce value
Rotating category
Often 5% in quarterly categories
Someone willing to activate and track categories
Easy to miss activations or spend outside the cap
How We Ranked These Cashback Cards
We did not rank cards only by the highest advertised percentage. That would be lazy and, in many cases, wrong. A 5% card is not better than a 2% card if the 5% applies only to a tiny category you rarely use.
Our ranking gives more weight to effective earn rate, redemption flexibility, annual fee, bonus value, category caps, and how easy the card is to use without turning your wallet into a spreadsheet. We also look at the Schumer Box terms: purchase APR, penalty APR, late fees, foreign transaction fees, and balance transfer fees.
That last part matters. Cash back is a reward. APR is a cost. If you pay your statement balance in full every month, rewards can be real value. If you carry a balance, the interest cost usually matters more than the earn rate.
Ranking Criteria
Effective earn rate after category caps and realistic spending patterns.
Redemption options, including statement credit, deposit, PayPal, Venmo, gift cards, or account credit.
Annual fee and whether the card can beat a no-fee alternative after the fee is counted.
Welcome bonus value compared with the required spending amount.
Schumer Box cost terms, especially purchase APR, penalty APR, late fees, balance transfer fees, and foreign transaction fees.
Ease of use, including whether categories activate automatically or require quarterly action.
Detailed Comparison: Earn Rates, Redemption, Bonuses, and Fees
Cashback cards no annual fee are popular for a good reason: you do not need to beat a fee before you start winning. Still, no annual fee does not mean no cost. The real cost appears if you carry a balance, miss a payment, use the card abroad, or redeem rewards at poor value.
The table below focuses on the parts that usually change the decision: what the card earns, how you can redeem, and who should care. Always confirm final rates and fees in the issuer's current terms before applying, because card offers can change by channel and applicant profile.
Card
Highest practical cashback
Base rate
Redemption notes
Best use case
PayPal Cashback Mastercard
3% on PayPal purchases
1.5% elsewhere
Redeem cash rewards to PayPal
Online shoppers who already use PayPal checkout
Venmo Credit Card
3% top eligible category
1% other eligible purchases
Rewards fit the Venmo app ecosystem
People whose spending categories change month to month
Wells Fargo Active Cash
2% on purchases
2%
Redeem through Wells Fargo Rewards, including account credit and eligible PayPal checkout
One-card simplicity
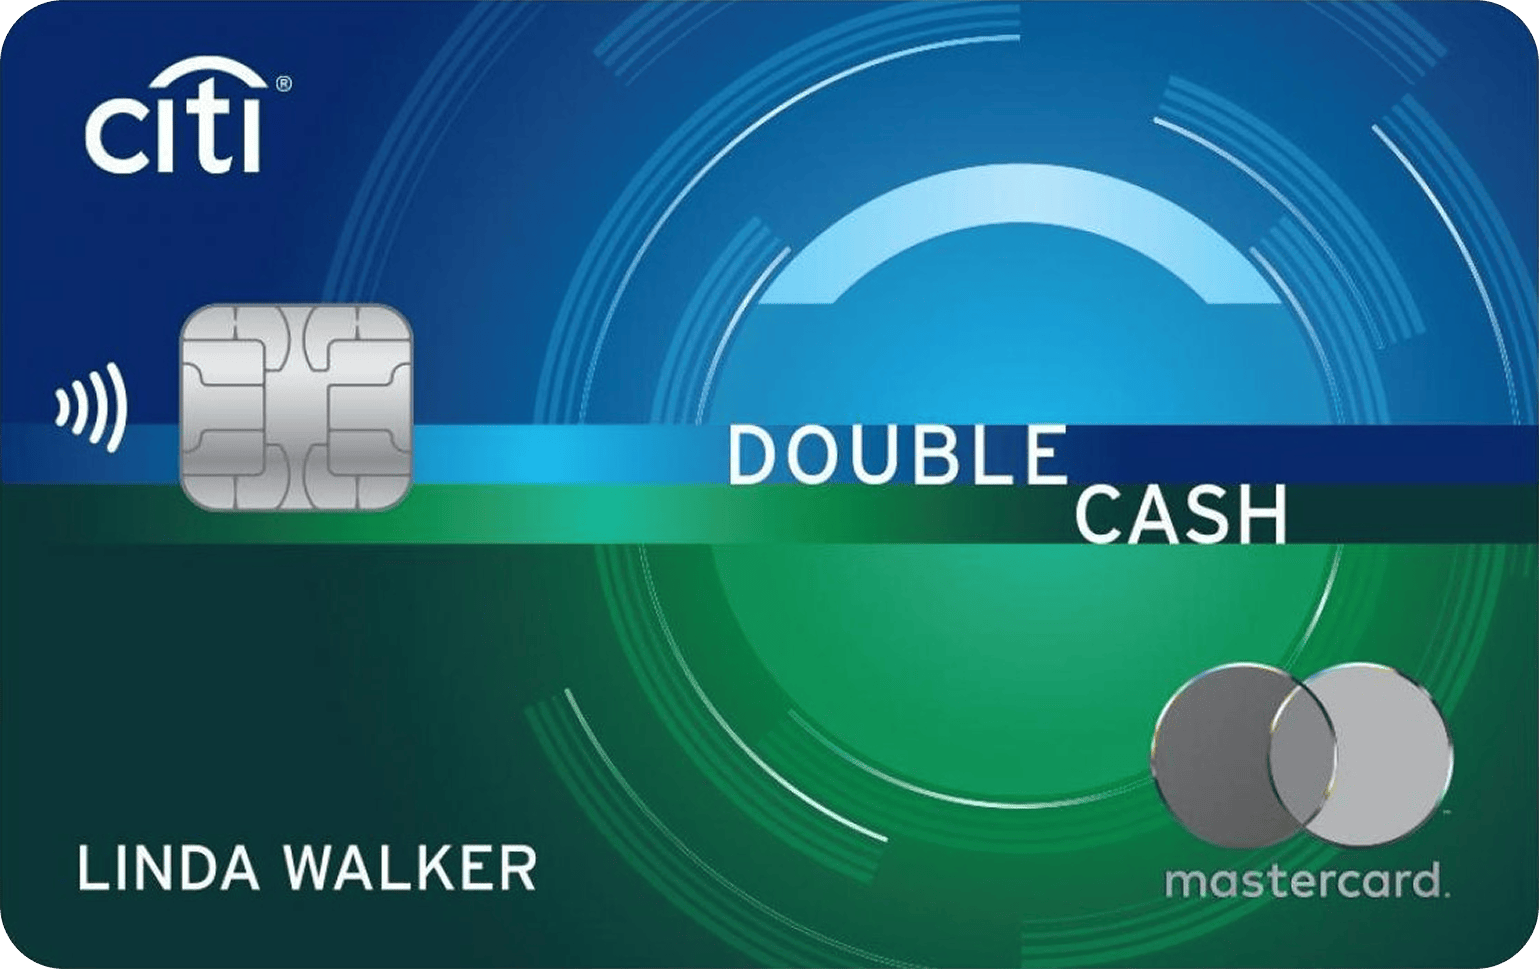
Citi Double Cash
2% total cash back
2% after payment
1% when you buy and 1% as you pay
People who want simple cash back and pay on time
Chase Freedom Flex
5% quarterly categories up to cap
1%
Requires activation for rotating categories
Hands-on optimizers
Blue Cash Everyday
3% in U.S. supermarkets, U.S. gas stations, and U.S. online retail up to caps
1%
Reward Dollars redeemable as statement credit
Families with grocery, gas, and online retail spend
U.S. Bank Cash+
5% on two selected categories up to quarterly cap
1%
Cash back through Rewards Center and Real-Time Rewards
People with predictable bills or chosen categories
Card-by-Card Breakdown
Here is how each card earns its place. This is where the headline earn rate meets real life. A card can look average on paper and still be perfect for you if it covers the place where most of your spending happens.
PayPal Cashback Mastercard: Best for PayPal Checkout
PayPal Cashback Mastercard is strongest when PayPal is already part of your checkout routine. It earns 3% back on PayPal purchases and 1.5% everywhere else Mastercard is accepted. There is no annual fee and no rotating category schedule to track.
That 3% PayPal category can be useful for online retail, subscriptions, delivery apps, and merchants where PayPal is a payment option. The card is less compelling as a pure everyday card because 1.5% on non-PayPal purchases trails the 2% flat-rate cards in this list.
Best fit: you frequently choose PayPal at checkout and want cash rewards deposited back into the PayPal ecosystem. Skip it as your only card if most of your spending happens in person and you can qualify for a 2% flat-rate card.
Venmo Credit Card: Best for Automatic Categories
Venmo Credit Card has a clever structure. It automatically earns 3% cash back on your top eligible spend category, 2% on the next, and 1% on other eligible purchases. Categories include areas such as grocery, dining and nightlife, travel, transportation, bills and utilities, gas, entertainment, and health and beauty.
The important phrase is automatic. You do not need to predict your spending before the month starts. Venmo sorts the top categories for you, which makes it friendlier than cards that require activation or category selection.
Best fit: you already use Venmo and want a category card that adapts to your actual spending. Skip it if you want a clean 2% card for every purchase or if you prefer redeeming outside an app-based ecosystem.
Wells Fargo Active Cash and Citi Double Cash: Best Flat-Rate Pair
Wells Fargo Active Cash is the cleanest flat-rate option in this group: unlimited 2% cash rewards on purchases, a $0 annual fee, and a published welcome bonus offer that has recently been $200 after $500 in purchases in the first three months. It is the card I would consider first if someone asked for one simple cashback card and did not want category homework.
Citi Double Cash is the classic alternative. It earns 1% when you buy and 1% as you pay, for 2% total cash back if you handle the bill correctly. That structure quietly teaches the right habit: you only get the full value when you pay. For more about Citi as a banking brand, see our Citi review.
Best fit: people who want a base card. Use one of these for purchases that do not earn a higher rate elsewhere. Then add a grocery, gas, PayPal, Venmo, or rotating-category card if your spending justifies the extra card.
Chase Freedom Flex, Blue Cash Everyday, and U.S. Bank Cash+: Best for Category Optimizers
Chase Freedom Flex is built for people who pay attention. It can earn 5% cash back on combined purchases in quarterly bonus categories up to the quarterly cap when you activate. It also earns extra on Chase Travel, dining, and drugstores. That is a lot of value if you use the card deliberately.
Blue Cash Everyday from American Express is more stable. Its strongest categories are U.S. supermarkets, U.S. gas stations, and U.S. online retail purchases, each with an annual cap before the rate drops. This makes it easier to plan around than a rotating-category card.
U.S. Bank Cash+ gives you more control. You choose two 5% categories each quarter and one 2% everyday category. That can be powerful for bills or predictable expenses, but it also creates another quarterly task.
Best fit: households with clear spending patterns. If you know where your money goes, category cards can beat a flat-rate card. If you do not want to track categories, keep your setup simpler.
How to Redeem and Stack Cashback Without Overcomplicating It
Cash back usually redeems as a statement credit, bank deposit, check, gift card, app balance, or checkout credit. The best redemption is the one that gives you full value and fits your routine. Do not redeem for merchandise or gift cards unless the value is clear.
For most people, the clean setup is a two-card wallet. Use a 2% flat-rate card for everything, then add one bonus card for your biggest category. Example: Wells Fargo Active Cash for all uncategorized spending plus Blue Cash Everyday for groceries, gas, and online retail. Or Citi Double Cash for general spend plus PayPal Cashback Mastercard for online PayPal purchases.
If you enjoy optimization, add a rotating category card. Chase Freedom Flex can be useful when the quarterly categories match places you already shop. But if you find yourself buying things only because a category pays 5%, the card is running the show. That is backwards.
Simple Cashback Stack
Pick a flat-rate base card for all spending that does not earn a bonus elsewhere.
Add one card for your largest recurring category, such as groceries, gas, online retail, dining, PayPal, or Venmo.
Set autopay for at least the statement balance if your budget can support it.
Redeem cash back at full value as a statement credit, deposit, or app balance you actually use.
Review the setup twice a year. If a card is not earning enough to justify attention, remove it from the rotation.
Who Each Cashback Card Is Best For
The best cashback card is usually obvious once you stop asking which card is best overall and start asking which card is best for your next $1,000 of spending.
A set-and-forget spender should usually start with a 2% flat-rate card. A grocery-heavy household should look at supermarket cards. A PayPal-heavy online shopper should consider PayPal Cashback Mastercard. A Venmo user who wants automatic category sorting should look at Venmo Credit Card.
If your credit score is still recovering, rewards should be secondary. Focus on approval odds, fees, deposit requirements, reporting to all three credit bureaus, and payment history. Rewards can come later.
If you are...
Start with...
Why
A one-card person
Wells Fargo Active Cash or Citi Double Cash
2% flat-rate value is hard to beat for simplicity
A PayPal checkout regular
PayPal Cashback Mastercard
3% on PayPal purchases can beat most general cards
A Venmo app user
Venmo Credit Card
Automatic 3% and 2% top-category structure reduces tracking
A grocery and gas spender
Blue Cash Everyday
3% in common U.S. household categories up to annual caps
A category optimizer
Chase Freedom Flex or U.S. Bank Cash+
Higher ceiling if you activate, select, and use categories correctly
A credit builder
A secured or low-score card first
Approval, reporting, and low fees matter more than rewards
Your Rights: Rewards Terms, CARD Act Disclosures, and Schumer Box Costs
Credit card rewards sit on top of a regulated credit product. That means the rewards page is not the only document that matters. You should also review the application disclosures, credit card agreement, and the Schumer Box.
The CFPB maintains a credit card agreement database and Regulation Z requires key disclosures to appear on or with card applications and solicitations. That is where you compare APRs, fees, grace periods, and penalty terms. For cashback cards, also read the reward-program terms. Look for redemption minimums, category exclusions, expiration rules, account-closure rules, and forfeiture language.
The CFPB has also warned that rewards programs can create unfair or deceptive issues when consumers do not receive the value they were led to expect. Translation: if a bonus looks unusually generous, read the conditions before you spend toward it.
Frequently Asked Questions
What is the best cashback credit card overall?
For most people, the best starting point is a no-annual-fee flat-rate card that earns around 2% on everyday purchases. After that, add one category card for your biggest spending area, such as groceries, gas, dining, PayPal, Venmo, or rotating categories.
Are flat-rate cashback cards better than rotating category cards?
Flat-rate cards are better if you want simplicity. Rotating category cashback cards can earn more, often around 5% in selected categories, but they require activation, category tracking, and attention to quarterly spending caps.
Is cash back from a credit card taxable?
Cash back earned from personal purchases is generally treated like a rebate or discount. Referral bonuses, business rewards, or rewards not tied to purchases can be different, especially if you receive a tax form.
What is the best cashback card for groceries and gas?
Blue Cash Everyday is a strong no-annual-fee option for groceries and gas because it earns 3% at U.S. supermarkets and U.S. gas stations up to annual category caps, then 1%. Venmo can also work if groceries or gas are among your top eligible categories.
Do cashback cards with no annual fee still have fees?
Yes. A $0 annual fee does not remove other costs. You still need to check the Schumer Box for purchase APR, penalty APR, late fees, balance transfer fees, cash advance fees, and foreign transaction fees.
Should I get a cashback card if I carry a balance?
Usually no. If you carry a balance, interest charges can wipe out your cash back quickly. Focus first on a lower APR, a payoff plan, or a balance transfer strategy before optimizing rewards.